
FHA Loan · Government‑backed, forgiving credit
FHA Loan: Government‑backed, low down payment, forgiving credit.
FHA loans are insured by the Federal Housing Administration and designed for borrowers with lower credit scores or limited down payments — purchases, cash-out, rate & term, and Streamline refinances on owner-occupied 1–4 unit homes.
- 3.5% Down at 580+ — 500–579 credit is accepted with 10% down. see how it works →
- FHA Cash-Out to 80% — Access your equity with credit guidelines more forgiving than conventional.
- FHA Streamline — Minimal docs, no appraisal, all credit considered — even on a former home you now rent out.
- Rental Units Help You Qualify — Buy a 2–4 unit home, live in one unit, and let the other units’ rent count toward qualifying.
Or skip the form — call or text 949-868-2422
- 5.0 verified client reviews
- NMLS #1996696
- Irvine, CA · 100+ lender network
60 seconds · no hard credit pull · never sold
Is this for your primary residence?
Purchases & cash-out need owner occupancy — an FHA Streamline works on a former primary you now rent out
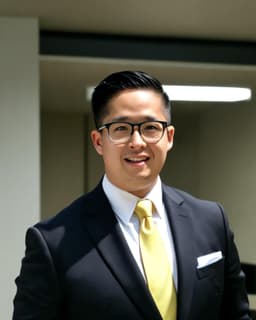
You’ll work directly with Anthony HuynhVice President · NMLS #1996696
- Credit considered from
- 500
- Max cash-out LTV
- 80%
- Refinance option
- Streamline
- Owner-occupied
- 1–4 units
Program terms depend on credit profile, LTV, property type, occupancy, and loan specifics, and are subject to change. All loans subject to credit approval.
Run the Numbers
Run your FHA numbers.
Enter your numbers for a quick estimate — then turn it into real numbers with the funnel or a call.
FHA Loan Calculator
Low down payment, flexible credit. Estimate an FHA purchase or cash-out refinance.
Your FHA loan
FHA cash-out: 80% LTV max, owner-occupied, no late payments in the last 12 months.
What your cash-out can do
- Pay off credit cards & auto loans — one payment
- Fund the next property’s down payment
- Renovations that add value
- Cash reserves for what’s next
Opens the 60-second options check with your numbers filled in — no hard credit pull.
Calculator results are estimates only and do not constitute a loan offer, pre-approval, or commitment to lend. Actual terms may vary.
Know Before You Apply
Can we fund your deal? Check before you apply.
The FHA Loan guidelines, plainly stated. Requirements vary by lender and scenario — a quick call confirms yours.
FHA Loan requirements
What you need
- Minimum Credit Score: 580 (3.5% down) / 500 (10% down)
- Cash-Out Max LTV: 80%
- Mortgage Insurance: 1.75% upfront + annual MIP
- Payment History: No late payments in the last 12 months
- Property Type: Owner-occupied 1–4 units (Streamline: former primary OK)
- Where we lend: Available for primary residences in 30 states — see every state
General guidelines only, not a commitment to lend. Gray-area scenario? Call or text 949-868-2422.
5 out of 5 stars
“Anthony was extremely helpful and responsive. He quickly found out what we needed and made it happen. Excellent service!”
Jesse W · Pullman, WA · Aug 2026Verified client review 5 out of 5 stars
“The process from start to finish was seamless. Though I had all the required documentation and qualifications, but Anthony was always communicating next steps.”
Charles A · Philadelphia, PA · Aug 2026Verified client review 5 out of 5 stars
“Immediate assist with loan process, willing to help to close out the deal ASAP”
Cuong L · Philadelphia, PA · May 2026Verified client review
FAQ
Frequently Asked Questions
Common questions about the FHA Loan.
What’s the minimum credit score for an FHA loan?
580 for the minimum 3.5% down payment; scores from 500 to 579 are accepted with 10% down. FHA also looks for no late payments in the last 12 months. We’ll confirm where your file lands.
How does FHA mortgage insurance (MIP) work?
FHA loans carry a 1.75% upfront mortgage insurance premium (which can be financed into the loan) plus an annual premium paid monthly — about 0.50–0.55% on most loans, higher on large balances. Depending on your down payment, MIP may remain for the life of the loan; refinancing into a conventional loan later is the most common way to remove it.
Can I use an FHA loan to buy an investment property?
No. FHA loans are for primary residences only. However, you can purchase a 2-4 unit property with an FHA loan if you live in one of the units — rental income from the other units may help you qualify.
Can gift funds cover my down payment?
Yes. Your entire FHA down payment can come from gift funds from family or other approved sources, which makes FHA a popular first-time buyer path.
Related Programs
Other programs worth a look.
Not quite the right fit? These programs solve neighboring scenarios — or let the funnel route you.
- Classic
Conventional Loan
The classic home loan for purchases and refinances, with removable PMI.
See options → - Veterans
VA Loan
Cash-out up to 100% LTV and no monthly mortgage insurance for those who served.
See options → - ★ Most Popular
5-Day HELOC
Tap equity without touching your first mortgage — up to 90% CLTV, no appraisal.
See options → - Not Sure?Let the funnel decide.Answer a few quick questions and we’ll route your scenario to the right program — 60 seconds, no hard credit pull.Find my program →
Ready to explore FHA Loan?
Answer a few quick questions and get a personalized strategy recommendation — including whether FHA is right for your situation. No hard credit pull.
Prefer a set time? Book a call · Ready to apply? Start your full application
FHA-approved lender. Not affiliated with or acting on behalf of HUD/FHA.
West Capital Lending, Inc. is an Equal Housing Lender. We do not discriminate on the basis of race, color, religion, national origin, sex, handicap, or familial status.