
Conventional Loan · The classic, priced for good credit
Conventional Loan: The gold standard — priced for good credit.
Conventional loans conform to Fannie Mae and Freddie Mac guidelines and cover purchases and cash-out refinances on primary homes, second homes, and investment properties — with removable PMI and published below-620 exception paths.
- As Little as 3% Down — 3% down for first-time buyers, 5% standard. Investment purchases need 20% down.
- Removable PMI — PMI goes away at 20% equity — unlike FHA mortgage insurance, it doesn’t last the life of the loan.
- Cash-Out to 80% LTV — 80% on primary residences, 75% on investment properties.
- Below-620 Exception Paths — Purchases with 20% down (30% on investment), or refinances with your balance under 65% of value. see how it works →
Or skip the form — call or text 949-868-2422
- 5.0 verified client reviews
- NMLS #1996696
- Irvine, CA · 100+ lender network
60 seconds · no hard credit pull · never sold
Is this for your primary residence?
Primary residences, second homes, and investment properties all qualify
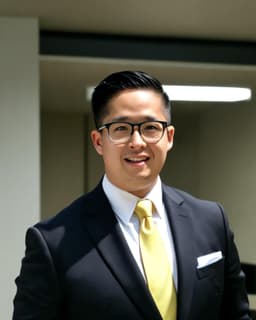
You’ll work directly with Anthony HuynhVice President · NMLS #1996696
- Minimum credit
- 620
- Exception paths available
- Below 620
- Max cash-out LTV, primary
- 80%
- PMI at 20% equity
- Removable
Program terms depend on credit profile, LTV, property type, occupancy, and loan specifics, and are subject to change. All loans subject to credit approval.
Run the Numbers
Run your Conventional numbers.
Enter your numbers for a quick estimate — then turn it into real numbers with the funnel or a call.
Conventional Loan Calculator
Estimate a conventional purchase or cash-out refinance, including PMI.
Your conventional loan
Conventional cash-out: 80% LTV max on a primary residence; investment properties to 75%.
What your cash-out can do
- Pay off credit cards & auto loans — one payment
- Fund the next property’s down payment
- Renovations that add value
- Cash reserves for what’s next
Opens the 60-second options check with your numbers filled in — no hard credit pull.
Calculator results are estimates only and do not constitute a loan offer, pre-approval, or commitment to lend. Actual terms may vary.
Know Before You Apply
Can we fund your deal? Check before you apply.
The Conventional Loan guidelines, plainly stated. Requirements vary by lender and scenario — a quick call confirms yours.
Conventional Loan requirements
What you need
- Minimum Credit Score: 620 (below-620 exception paths available)
- Minimum Down Payment: 3% first-time · 5% standard · 20% investment
- Cash-Out Max LTV: 80% primary · 75% investment
- PMI: If under 20% down — removable at 20% equity
- Below 620: Purchase: 20% down (30% investment) · Refi: balance under 65% of value
- Where we lend: Available for primary residences in 30 states; investment properties in 44 states plus Washington, D.C. — see every state
General guidelines only, not a commitment to lend. Gray-area scenario? Call or text 949-868-2422.
5 out of 5 stars
“Anthony was outstanding to work with throughout the entire loan process. He was extremely responsive, knowledgeable, and proactive at every step, which made the transaction smooth and stress-free.”
Ashish S · Mason, OhioVerified client review 5 out of 5 stars
“Anthony was extremely helpful and responsive. He quickly found out what we needed and made it happen. Excellent service!”
Jesse W · Pullman, WA · Aug 2026Verified client review 5 out of 5 stars
“The process from start to finish was seamless. Though I had all the required documentation and qualifications, but Anthony was always communicating next steps.”
Charles A · Philadelphia, PA · Aug 2026Verified client review
FAQ
Frequently Asked Questions
Common questions about the Conventional Loan.
What is a conventional loan?
A conventional loan is a mortgage that is not backed by a government agency (unlike FHA or VA loans). Most conventional loans conform to guidelines set by Fannie Mae and Freddie Mac, which set loan limits and underwriting standards.
What is the conventional loan limit?
Conforming loan limits are set annually and are higher in high-cost areas (like parts of California, New York, and Hawaii). Loans above these limits are called jumbo loans — we can quote current limits for your county.
Is PMI required on a conventional loan?
PMI (private mortgage insurance) is required when the down payment is less than 20%. PMI is cancelled automatically when you reach 22% equity (based on the original purchase price), and you can request cancellation at 20%. PMI costs vary by credit score and LTV.
What credit score is needed for a conventional loan?
620 is the standard minimum. Below 620 there are exception paths: a purchase with 20% down (30% on an investment property), or a refinance where your balance is under 65% of the home’s value.
Related Programs
Other programs worth a look.
Not quite the right fit? These programs solve neighboring scenarios — or let the funnel route you.
- Flexible Credit
FHA Loan
Government-backed financing for owner-occupied 1–4 unit homes.
See options → - Veterans
VA Loan
Cash-out up to 100% LTV and no monthly mortgage insurance for those who served.
See options → - Self-Employed
Bank Statement Loan
Qualify with 12–24 months of personal or business deposits instead of tax returns.
See options → - Not Sure?Let the funnel decide.Answer a few quick questions and we’ll route your scenario to the right program — 60 seconds, no hard credit pull.Find my program →
Ready to explore Conventional Loan?
Answer a few quick questions and get a personalized strategy recommendation — including whether Conventional is right for your situation. No hard credit pull.
Prefer a set time? Book a call · Ready to apply? Start your full application
West Capital Lending, Inc. is an Equal Housing Lender. We do not discriminate on the basis of race, color, religion, national origin, sex, handicap, or familial status.